Buying and selling a home at the same time in the GTA? Learn about equity, deposits, bridge financing, sale conditions, closing dates and failed-closing risks.
By Marco Momeni, Broker, RE/MAX Hallmark Realty
1. Should I sell my current home before buying my next home in the GTA?
There is no single correct answer. Whether you should sell first or buy first depends on your finances, how easy your current property is likely to be to sell, how difficult your next home may be to find, and how much financial risk you can comfortably carry.
Selling first gives you more certainty. Once your property has sold firmly, you know the actual sale price and can calculate much more accurately how much equity will be available for your next purchase.
The disadvantage is that you may sell before finding a suitable replacement property. That could mean negotiating a longer closing date, arranging temporary accommodation or renting until the right home becomes available.
Buying first gives you certainty about where you are going , but it creates a different risk. If your existing property takes longer to sell than expected—or sells for less than you anticipated—you may have to carry two properties or find additional financing.
Before buying first, I would want a homeowner to know:
- what the existing property can realistically sell for;
- approximately how much net equity will remain after the mortgage and selling expenses;
- where the deposit for the next purchase will come from;
- whether the new mortgage has been properly reviewed with the lender or mortgage professional;
- whether carrying both homes temporarily is financially possible; and
- what happens if the existing property does not sell as quickly as expected.
The mistake is not necessarily buying first or selling first. The bigger risk is committing to one transaction without understanding how it affects the other.
2. How can I use the equity in my current home for the deposit and down payment on my next property?
Having substantial equity in your current home does not necessarily mean that money is available when you need to make the deposit on your next purchase.
This is one of the most common practical problems when buying and selling at the same time.
For example, you may have $500,000 of equity in your current property, but most of that money normally becomes available only when the sale closes. If you find your next home today, however, the deposit required under your new Agreement of Purchase and Sale may be due much sooner.
That is why I separate three different numbers:
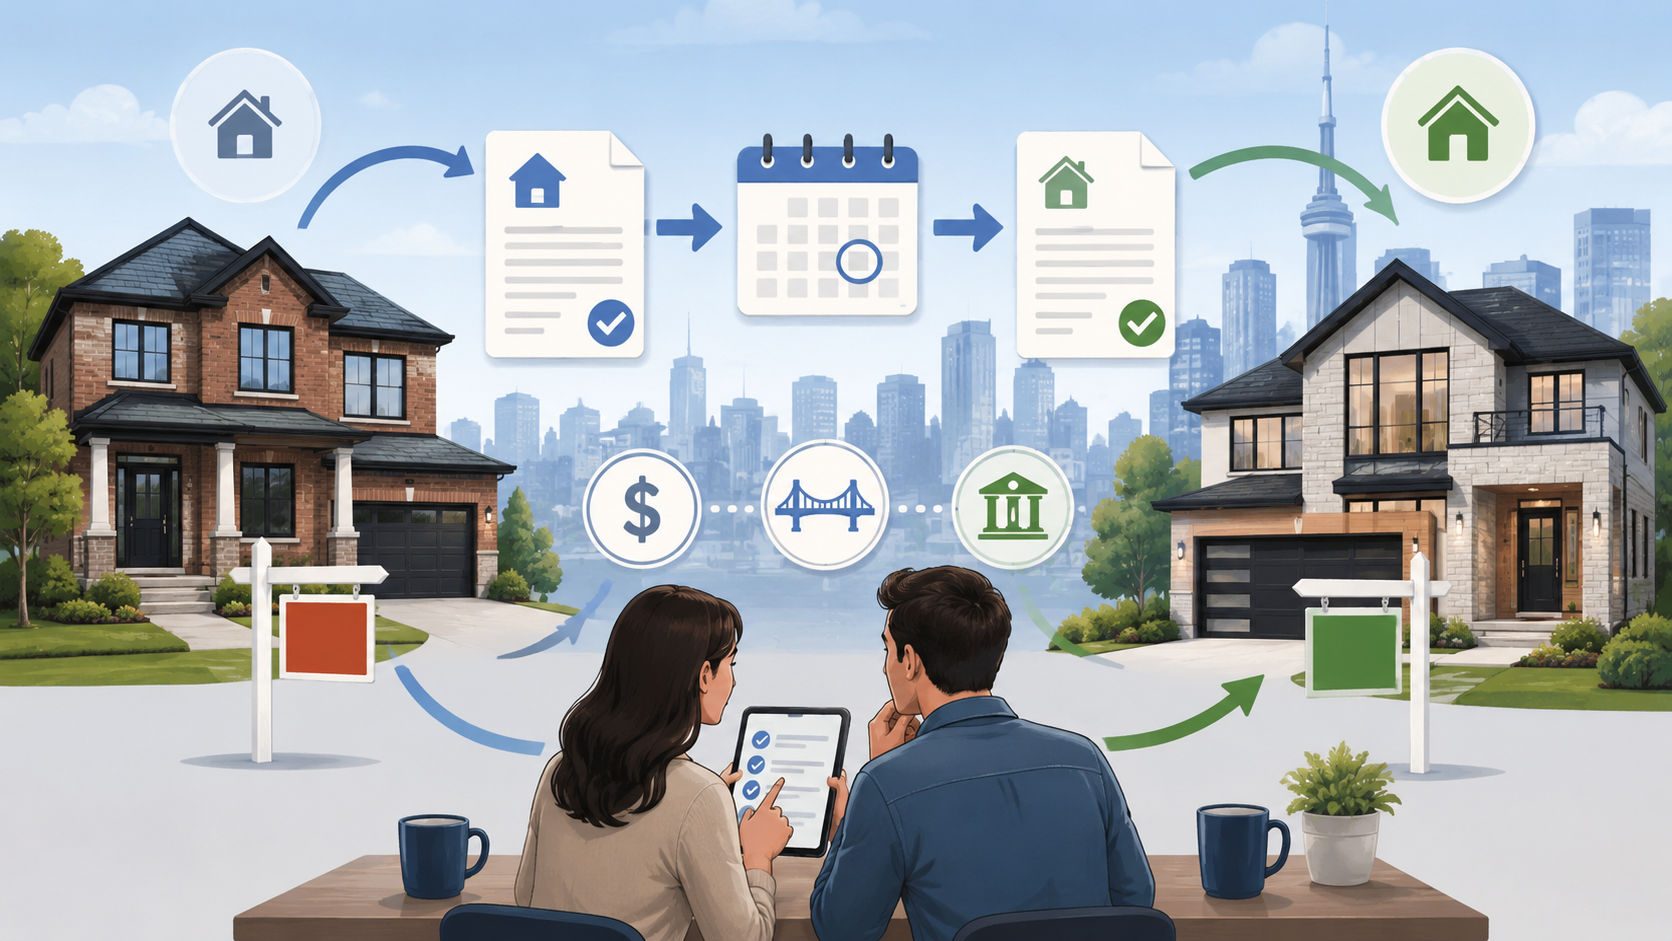
Deposit available now → down payment required on closing → equity received when the existing home closes
They are connected, but they are not the same thing.
Depending on the homeowner's circumstances and lender approval, accessible funds could come from savings, an existing home equity line of credit or another approved borrowing arrangement secured against the current home.
The Financial Consumer Agency of Canada confirms that homeowners may be able to borrow against home equity using products such as a home equity line of credit, home equity loan or second mortgage. Qualification requirements, borrowing limits, interest and other costs apply.
The important point is to solve the deposit question before making the offer.
A homeowner can be equity-rich and still have a cash-flow problem if the equity cannot be accessed at the time the deposit is required.
You can also use the Mortgage Affordability Calculator on MarcoMomeni.com as a preliminary planning tool. Calculator results are general estimates only. Individual circumstances, lender requirements, debts, income and the structure of the purchase and sale can result in someone qualifying for more or less than the estimate. Financing should be confirmed with a qualified lender or mortgage professional before making a firm purchase commitment.
3. What is bridge financing, what does it cost, and what are its limitations?
Bridge financing is short-term financing that can help when your new home closes before the sale of your existing home closes.
A simple example:
Your new purchase closes on June 10.
Your existing home has already been sold firmly, but that sale does not close until June 25.
The equity is coming, but you will not receive the sale proceeds for another 15 days. Approved bridge financing may allow you to use some of that expected equity to complete the new purchase during the gap.
TD describes bridge financing as a short-term loan used when the purchase and sale closing dates do not match and says its bridge financing is typically available for a maximum period of 90 days. That is TD's current policy, however—not a universal industry rule. Other lenders may have different limits and requirements.
There is one major limitation many homeowners do not realize:
Bridge financing generally does not mean you can buy a property, leave your existing home unsold indefinitely and simply borrow against the expected future sale.
RBC currently states that a firm sale agreement must already be in place on the existing home to qualify for its bridge financing.
That means this assumption can be dangerous:
“I'll buy the new house first. If mine doesn't sell, I'll just get bridge financing.”
You may not qualify for a traditional bridge loan until your existing property has actually been sold firmly.
Bridge financing also has a cost. There can be:
- interest;
- lender or administration fees;
- legal costs;
- limits on how much can be advanced; and
- a maximum period the lender will allow the bridge loan to remain outstanding.
Exact rates, fees, limits and qualification requirements vary by lender and borrower, so they should be confirmed before the closing dates are structured around bridge financing.
The right questions to ask your lender are:
How much can I bridge? For how long? What will it cost? And what happens if my existing sale closing is delayed?
4. Should I make my purchase conditional on the sale of my current property?
A purchase can be made conditional upon the sale of the purchaser's existing property . This can reduce the risk of committing to a new home before knowing that the current property has sold.
In simple terms, the buyer agrees to purchase the new property provided the buyer's existing property is sold within the period and on the terms set out in the Agreement of Purchase and Sale.
This can be valuable for a homeowner who cannot safely carry both properties.
The disadvantage is that the seller of the property you want is being asked to accept uncertainty. If another buyer is prepared to make a firm offer without a sale-of-property condition, that offer may be more attractive to the seller.
The condition can include an escape clause
One way of making a sale-of-property condition more acceptable to a seller is to negotiate an escape clause , sometimes called a kick-out clause.
The seller may be allowed to continue marketing the property while the original buyer tries to sell their existing home.
If the seller receives another acceptable offer, the original buyer can then be given a specified period under the agreement to decide whether to remove the sale condition and make the purchase firm.
If the buyer cannot or does not want to remove the condition within that contractual period, the original agreement may be terminated according to its wording, allowing the seller to proceed with the other offer.
Ontario legal commentary confirms that escape clauses can be structured this way and that the exact notice procedure and deadlines are important.
There is no automatic 24-, 48- or 72-hour rule that applies to every transaction. The time period and procedure are negotiated and written into the agreement.
A sale-of-property condition can also address:
- exactly which property the purchaser must sell;
- the deadline for that sale;
- whether the seller can continue marketing;
- what happens if another offer is received;
- how notice must be delivered;
- how long the purchaser has to respond; and
- how the condition is satisfied, waived or terminated.
Because the precise wording can have significant legal consequences, the clause should be drafted appropriately for the transaction and reviewed by an Ontario real estate lawyer where legal advice is required.
5. How should I coordinate the closing dates, and should both transactions close on the same day?
Closing both properties on the same day may appear to be the simplest solution, but it is not automatically the lowest-risk option.
The attraction is obvious:
You sell your current home, receive the proceeds and use that money to complete the purchase of the next property.
But the two transactions then become directly dependent on each other.
If the sale of your existing property does not close when expected, the funds required for your purchase may also be delayed.
One alternative, where financing permits it, is to have the new purchase close several days before the existing home and use approved bridge financing for the short gap.
That can provide time to move gradually and reduce the logistical pressure of trying to complete two transactions and a move on the same day.
Another approach is to sell first and have the purchase close later. That avoids carrying two properties but can create a temporary accommodation problem if there is a gap.
When planning the dates, consider:
- whether your existing property has already sold firmly;
- whether bridge financing has been approved;
- when the equity from the existing property will become available;
- how much overlap you can afford;
- the other buyer's and seller's preferred closing dates;
- moving logistics; and
- what happens if either closing is unexpectedly delayed.
Bridge financing exists specifically because purchase and sale dates do not always line up perfectly.
The objective should not be to make the dates look perfect on paper. It should be to create a structure that still works if something takes slightly longer than expected.
6. If I sell first, how long should I ask for before closing so I have enough time to find my next home?
A longer closing can give you additional time to find your next property, but there is no single closing period that works for every homeowner.
The right amount of time depends largely on what you are trying to buy.
If you are moving into a property type with substantial inventory and many acceptable alternatives, finding the next home may be relatively straightforward.
It can be very different if you need:
- a particular neighbourhood;
- a specific school boundary;
- a rare lot size;
- a certain type of luxury home;
- a bungalow or other limited property type; or
- a narrow combination of price, location and features.
The closing date is also negotiated with the buyer of your existing property. That buyer may have a lease ending, a mortgage commitment, another home to sell or their own closing date to coordinate.
So before accepting an offer with a particular closing date, ask another question:
What will I do if I still have not found the right property when that date arrives?
Possible backup plans can include:
- temporary rental accommodation;
- staying with family;
- short-term storage;
- renting for a longer period; or
- adjusting the search criteria rather than buying the wrong property because the clock is running out.
Selling first reduces uncertainty about your finances.
It does not eliminate uncertainty about where you will live next.
7. What happens if the buyer of my current home does not close when I am supposed to close on my new home?
This can become a serious problem because the failure of your buyer to close does not automatically cancel or extend your obligation to complete your own purchase .
If you are relying on the proceeds from the sale of your existing home to complete the next purchase, the two transactions are financially connected.
A firm Agreement of Purchase and Sale is a binding contract. RECO specifically warns buyers that failing to provide an agreed deposit does not automatically make the transaction disappear; failing to comply with contractual obligations can constitute a breach and have serious legal and financial consequences.
If your buyer cannot close, your real estate lawyer and lender should be contacted immediately.
Depending on the circumstances, possible issues could include:
- negotiating an extension;
- obtaining additional short-term financing if available;
- additional interest or carrying costs;
- additional legal costs; and
- pursuing whatever contractual remedies your lawyer advises are available.
The critical point is this:
Do not assume that because your buyer failed to close, you are automatically excused from closing your own purchase.
Before entering two dependent transactions, it is worth discussing the worst-case scenario with your lender and lawyer.
For example:
What happens if my sale is delayed by one day?
What if it is delayed by a week?
Can my bridge financing be extended?
Is another financing option available?
What additional costs could result?
These questions are much easier to deal with before the problem occurs than on closing day.
8. I found the right home, but my current property is not even listed yet. What are my realistic options?
You still have several options, but this is also one of the situations where fear of losing the new property can lead homeowners into unnecessary financial risk.
Option 1: Buy first
This can work if you have sufficient financing, accessible deposit funds and the ability to manage the risk if your current property takes longer to sell.
But the plan should be based on a realistic sale estimate—not the highest price you hope your property might achieve.
You also need to understand what happens if the property does not sell within the expected period.
Option 2: Make the purchase conditional on selling your existing property
A condition on the sale of the purchaser's property can protect you from having to complete the new purchase if the current property does not sell according to the condition.
Whether the seller will accept that condition depends on the circumstances and negotiating environment.
An escape clause may make the arrangement more attractive to the seller because the seller can potentially continue marketing the property while you try to sell yours.
Option 3: List your current home immediately
Sometimes the solution is not complicated financing.
If the existing property can be prepared and listed quickly, it may be possible to negotiate sufficient time on the purchase while simultaneously getting the current property sold.
The feasibility of this strategy depends heavily on the specific property and current conditions in its local market.
Option 4: Do not buy that particular home
This can be the hardest option when you believe you have found the perfect property.
But one home should not force you into a financial commitment you cannot safely complete.
After 24 years working with Toronto and GTA homeowners, my approach is to look at the purchase and sale as one combined transaction plan .
Before deciding what to do, I want to understand:
Expected sale price → available equity → available deposit → financing → purchase strategy → closing dates → backup plan
The objective is not simply to secure the next home.
It is to make sure you can successfully complete both transactions.
Planning to Buy and Sell at the Same Time?
Buying and selling simultaneously can work very well when the two transactions are planned together from the beginning.
Before making a commitment, understand:
- whether buying or selling first makes more sense for your situation;
- where your next deposit will come from;
- when your existing equity will actually become available;
- whether bridge financing is available and what its limitations are;
- whether a sale-of-property condition should be considered;
- how the two closing dates should be structured; and
- what happens if either transaction is delayed.
If you are planning a move within Toronto or the GTA, I can help you evaluate the sale and purchase together before you commit to either side.
Marco Momeni Broker, RE/MAX Hallmark Realty 24 Years of Toronto & GTA Real Estate Experience $1B+ Career Sales 416.700.7070 MarcoMomeni.com
This article provides general real estate information and is not legal, mortgage or financial advice. Agreements and contractual clauses should be reviewed with a qualified Ontario real estate lawyer where appropriate, and financing should be confirmed with your lender or mortgage professional.